


Bond Basics: Why do bond prices and interest rates move in opposite directions?
The bond market is often relatively unknown to private investors. In this post, we want to explain the most fundamental (and most misunderstood) law of the bond market: the inverse relationship between a bond’s price and market interest rates.
This was anticipated in the previous post with the explanation of what correlation is, that is, the relationship that exists between the movements of one asset with respect to another.
What is a bond?
A bond is a debt instrument issued by governments or corporations for the purpose of raising funds. The issuer agrees to repay the borrowed amount at a later date and to pay periodic interest over the term of the loan. Investors who purchase the bond agree to lend money to the issuer in exchange for receiving a certain interest rate over the life of the bond and will be repaid the full principal at maturity.
For example, the issuer could issue a bond with a face value of 100, which pays 3% annual interest (the coupon) for the next 10 years and repay the face value of 100 at maturity.
The bond buyer will invest 100 and earn a 3% annual return for 10 years. After 10 years (unless the borrower defaults), they will recover their entire capital.
Throughout its life, the bond also has a market price and can be bought and sold, meaning that, for example, the original buyer could sell the bond to someone else.
Inverse relationship between bond prices and interest rates
The bond price is not fixed and can fluctuate. Changes in the bond’s market price largely depend on movements in interest rates.
Here comes the most basic, yet most difficult-to-swallow concept about bonds: the inverse relationship between interest rates and bond prices, meaning that when interest rates rise, bond prices fall, and vice versa.

How bond yield and profitability work
Imagine you buy a newly issued 10-year bond paying 3% annual interest for a price equal to 100. Also imagine that after you buy the bond, the general level of 10-year interest rates rises. So now other bonds, with the same risk and maturity characteristics as yours, offer a higher yield, say 4%.
Now let’s suppose you want to sell your bond. Who would be willing to buy it at the original price of 100 to earn a 3% annual yield? Probably no one, since it’s now possible to find bonds like yours that offer a 4% yield. An investor will only agree to buy your bond if they also earn 4%.
Since the annual interest payments (3%) are contractually fixed when the bond is issued, the only way for your bond to offer a 4% yield would be a reduction in price.
Imagine the price drops to 92. If someone buys your bond at the new price, they will pay 92 and be repaid at 100 in 10 years. This will result in a capital gain for the bond buyer.
Adding this gain to the periodic annual contractual payments of 3% offered by the bond, the buyer will obtain a total return that is roughly in line with the 4% offered by the newly issued bonds (which he would purchase at 100).
So, here’s why bond prices fall when interest rates rise. Of course, the opposite is true for a decrease in interest rates. Bond prices and interest rates move in opposite directions.
Chart of the evolution of government bond prices and interest rates
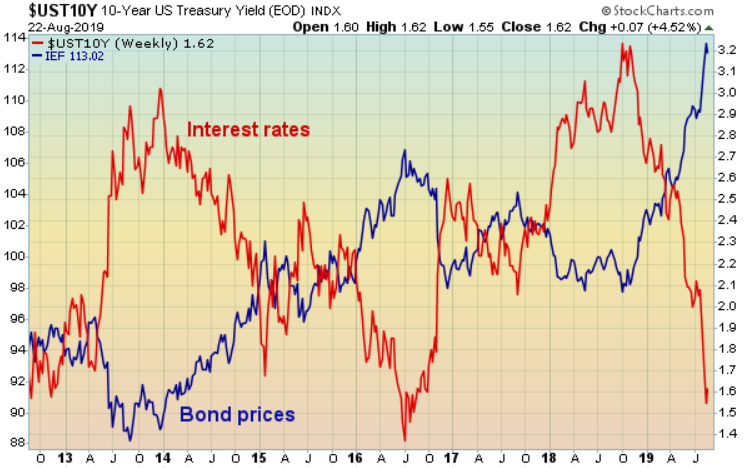
The chart below shows how the price of an ETF composed of U.S. government bonds with maturities between 7 and 10 years moves relative to 10-year U.S. interest rates.
As you can see, bond prices and interest rates tend to move in opposite directions for the reasons explained above.
What was explained above applies to bonds that have a coupon contractually fixed at the outset, which is the majority of bonds.
However, there are some bonds (called floating-rate bonds) for which the annual interest payments are not fixed, but are allowed to fluctuate with the level of interest rates. Thus, if interest rates change, the bond’s periodic payments will also change.
For this type of bond, there is no (or very limited) need for price adjustments, just like periodic payments to adjust to movements in interest rates.
Related posts:
 Permanent portfolios: the strategy for investing in any economic condition
 Characteristics of smart investors, according to experts
 Index Funds vs. ETFs: Which to Choose If You’re a Beginner
 How to Invest in ETFs: Beginner’s Guide
 Saving for Your Child’s Home Down Payment: Guide to Help Them Have Their Apartment at 18


